Your business
Invoice
No. INV-2026-001
| Description | Qty | Unit price | Amount |
|---|---|---|---|
| Add a line to get started. | |||
Subtotal£0.00
Total£0.00
A UK VAT invoice is issued by a VAT-registered business, normally within 30 days of the tax point. It shows your VAT registration number, the tax point, each line with its rate and net amount, and the total VAT in sterling. The generator below is set for the UK: add your VAT number and it prints one.
No sign-up · No watermark · Your data stays on your device
Your browser is blocking storage (private browsing?): this document will not be kept if you close the page. Download it before leaving.
This browser's storage is full: the document stays on screen but is no longer saved. Remove an image or delete old documents.
This document link is invalid or incomplete. Ask the sender to send it again.
Line deleted.
Amount due£0.00
| Description | Qty | Unit price | Amount |
|---|---|---|---|
| Add a line to get started. | |||
VAT Notice 700/21 lists them (§ 4.1): a sequential number; the time of supply, or tax point; the date of issue, if different; your name, address and VAT registration number; your customer's name and address; a description of what you supply; for each line, the quantity, the VAT rate and the amount excluding VAT; the total excluding VAT; the rate of any cash discount; the total VAT in sterling; and the unit price.
In the generator, your VAT number goes in “Your IDs and logo”, the tax point in “Number and dates”, and a cash discount in “Legal notices”. If you trade under another name, also show the name and address registered for VAT (VAT Notice 700, § 16.3.1).
You can issue a simplified invoice when the supply is £250 or less and your customer agrees (VAT Notice 700, § 16.6.1). It keeps your name, address and VAT number, the tax point, a description, and per rate the total including VAT. “Required details” says when the short form is enough.
The basic tax point is when goods are sent or a service is performed; an earlier invoice or payment, or an invoice issued within 14 days after it, becomes the tax point (§ 14.2). You normally issue the VAT invoice within 30 days of the tax point (§ 16.2.3). With a VAT number and no separate date, the generator prints “Date (tax point)”; fill in “Time of supply (tax point), if different” to print both dates.
You may invoice in any currency, but the total VAT must be shown in pounds (§ 16.4), converted at the UK market selling rate at the time of supply or at HMRC's period rate (§ 7.6). HMRC's monthly rates read as currency units per pound (1.3456 US dollars in October 2026): enter your rate that way in “Languages and currency”.
Your VAT registration number has 9 digits, and you cannot include VAT on your invoices until you get it (gov.uk, Register for VAT); without one, the generator adds no VAT.
A pro-forma should be clearly marked ‘this is not a VAT invoice’ (§ 17.3): the generator prints it on every UK proforma invoice. A credit note shows the number and date of the original invoice and the VAT credited in sterling (§ 18.2.3).
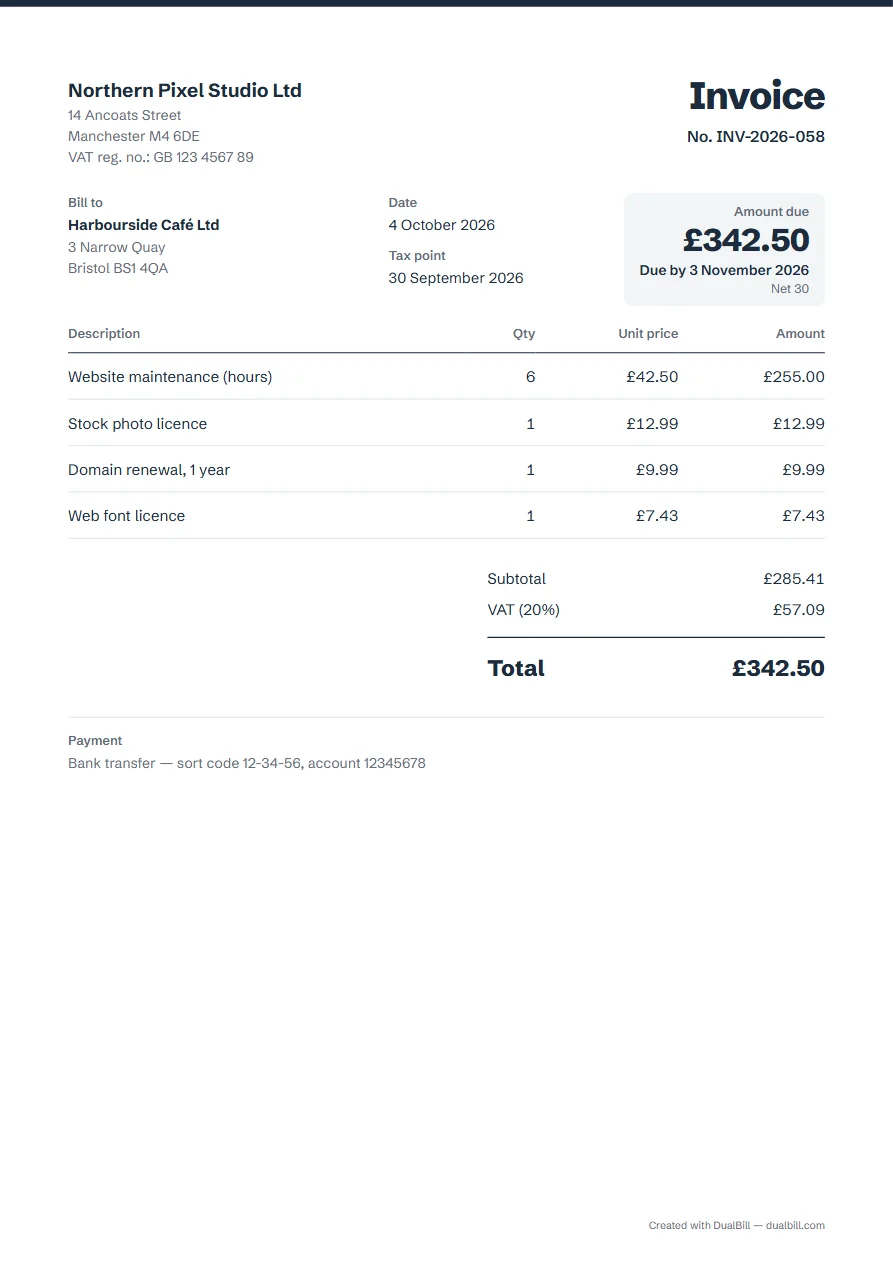
The generator rounds the VAT of each UK line to the nearest penny, as VAT Notice 700 allows (§ 17.5.1). In the example, the four lines (£255.00, £12.99, £9.99 and £7.43 at 20%) carry £51.00, £2.598, £1.998 and £1.486 of VAT, rounded to £51.00, £2.60, £2.00 and £1.49: £57.09, not the £57.08 of a single rounding. The VAT calculator rounds a single amount the same way.
No. You do not have to issue VAT invoices for zero-rated supplies, or to customers who are not VAT-registered (VAT Notice 700, § 16.2.1). HMRC notes that in practice you will probably issue one to any customer who asks.
Yes. HMRC may ask for an English translation of specific invoices within 30 days (§ 16.2.4). For a document in two languages, use the English–French or the English–Spanish invoice.
Not for goods traded with the EU: Northern Ireland businesses that trade goods with the EU follow VAT Notice 725, with an ‘XI’ prefix on their VAT number for those invoices. The generator doesn't apply those rules.
The government has announced mandatory e-invoicing for all VAT invoices from 2029. A PDF from this generator is not an electronic invoice under that future regime.
No VAT and no VAT number. As a sole trader, show your name and any business name, and an address where legal documents can be delivered if you use a business name; a limited company shows its full name as on its certificate of incorporation (gov.uk). More on the sole trader invoice page.